A Generation That May Never Be Able to Afford a Home
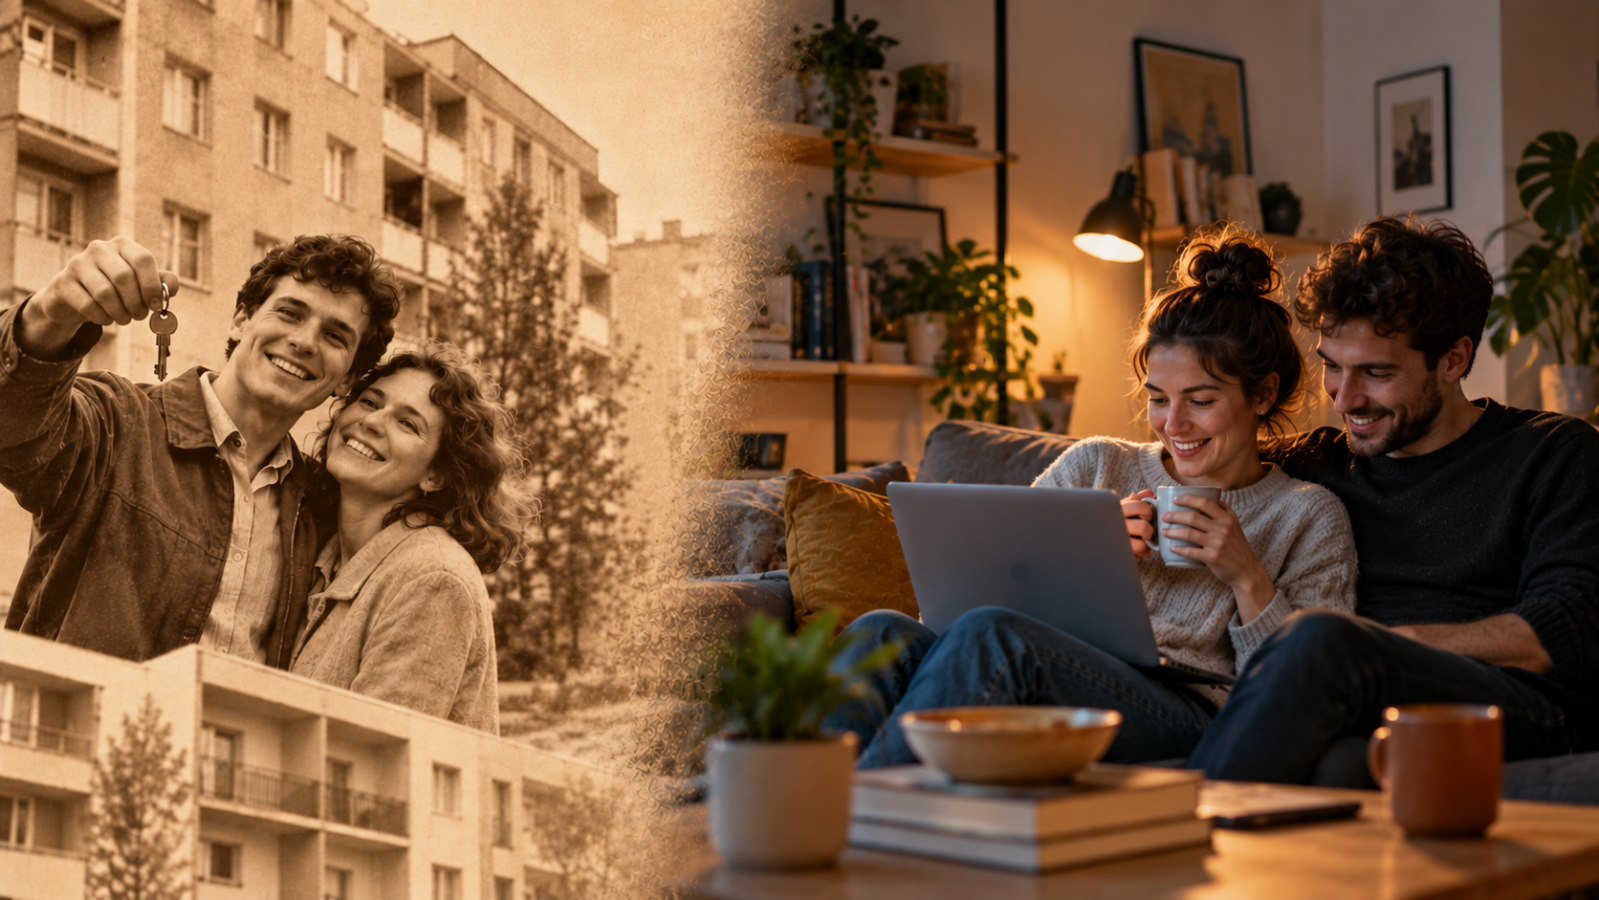
Many young people today are asking themselves whether they will ever be able to buy a home of their own. But perhaps there is a more important question: what if they never do? Does that automatically mean they will be poorer than their parents? Or will they simply build their wealth differently?
Their Parents Had an Opportunity That Won’t Come Again
For today’s generation of people in their sixties, owning a home was almost a given. After 1991, Czech municipalities began selling publicly owned apartments to their tenants, often for just a tenth of their market value. Prague alone sold most of its approximately 194,000 municipal apartments this way. Starting in 1994, members of housing cooperatives were also able to transfer their apartments into private ownership. As a result, an entire generation acquired the largest share of its wealth for a fraction of its actual value.
Today’s thirty-somethings have no such opportunity. Buying a new apartment in the Czech Republic requires roughly 13 years of gross annual salary, rising to around 15 years in Prague. Over the past decade, apartment prices have increased by more than 200%, while wages have risen by approximately 90%.
My colleague Ondřej Marek explored practical ways to achieve homeownership today in his article Young People and Homeownership: An Impossible Dream or a Matter of Planning?. Here, we’ll look at the other side of the coin: what happens when a large part of a generation never owns a home, and how they can still build financial security.
How Young People Manage Their Money Today
Young people are no less financially responsible than their parents. They simply face a different starting point.
According to a survey by Česká spořitelna and Evropa v datech, nearly half of Czechs spend more than 30% of their net income on housing, while 58% of people aged 18–29 live with their parents, at least part of the time.
At the same time, the way young people manage their money is changing. Today, 55% of Czechs consider themselves investors, compared with 41% just two years ago. The typical new investor is relatively young, and people under 30 are the most likely to invest through mutual funds and ETFs.
In other words, a generation that cannot afford to buy property is learning to buy a share of the global economy instead.
What This Means for the Economy
Wealth will shift from property to financial assets. Today, the vast majority of Czech households hold most of their wealth in real estate. If young people begin investing regularly instead of making mortgage payments, more money will flow into investment funds, stocks, and bonds. This could strengthen capital markets and corporate financing, but it also means household wealth will become more exposed to market fluctuations.
The end of forced saving. A mortgage has traditionally served as a form of automatic saving. With every payment, homeowners gradually build equity, whether they consciously intend to or not. Renters have no such built-in mechanism. Their wealth depends on whether they actually invest the difference between their rent and what a mortgage payment would cost.
This creates a risk of a generational divide: those who invest consistently and those who simply pay rent. After 30 years, the wealth gap between these two groups could be greater than the difference in their salaries.
A more flexible labor market. Renters can move more easily for better jobs, whether to another city or another country. An economy with a larger share of renters may become more mobile and productive. This is one of the benefits that rarely gets mentioned in discussions about housing.
A new challenge for retirement. Many of today’s retirees have relatively low housing costs because they own their homes outright. Future retirees who continue renting will need higher incomes even in retirement.
The government cannot close this gap on its own. It will need to be covered by the wealth people accumulate throughout their working lives. That makes regular investing far more important for a generation of renters than it was for their parents.
A more professional rental market. As demand for long-term rental housing increases, institutional landlords, municipalities, and housing cooperatives will likely play a greater role. Renting could become more stable and predictable than it is today, when most rental apartments are owned by individual landlords.
A Practical Example: How Much Wealth Can a Renter Build?
Let’s look at some actual numbers.
According to calculations by Hyponamíru.cz, the monthly mortgage payment for an average 60 m² apartment is currently around CZK 25,400, while renting a comparable apartment costs approximately CZK 19,900.
That means a renter can potentially save around CZK 5,500 per month. They also avoid having to provide CZK 1.2 million in upfront equity.
What happens if someone regularly invests several thousand crowns a month?
Assuming an average annual return of 6%, a reasonable long-term assumption for a globally diversified investment portfolio, the results would look like this:
|
Monthly investment |
After 20 years |
After 30 years |
Total contributions (30 years) |
|
CZK 3,000 |
CZK 1.4 million |
CZK 3.0 million |
CZK 1.1 million |
|
CZK 5,000 |
CZK 2.3 million |
CZK 5.0 million |
CZK 1.8 million |
|
CZK 7,000 |
CZK 3.2 million |
CZK 7.0 million |
CZK 2.5 million |
Someone who starts investing CZK 5,000 a month at age 30 and increases that amount by 3% each year as their income grows could accumulate around CZK 7 million by age 60.
Adjusted for inflation, that would be equivalent to approximately CZK 3.3 million in today’s money.
Such a portfolio could cover a substantial portion of rental expenses throughout retirement. And unlike an apartment, financial investments can be divided, sold gradually, or passed on to children with relative ease.
Of course, there is another side to this equation. Investment returns are never guaranteed, markets fluctuate, and portfolio values can decline in certain years. The strategy only works if investors remain disciplined during difficult periods and avoid withdrawing their money prematurely.
Key Takeaways
- Renting is not a failure. Paying rent without building any wealth is the real risk. Someone who consistently invests the difference between rent and a mortgage payment can potentially achieve financial security comparable to that of a homeowner.
- Time matters more than the amount invested. In our model, investment returns account for roughly two-thirds of the final portfolio value after 30 years, rather than the investor’s own contributions. Starting with CZK 2,000 a month at age 25 can be more beneficial than starting with CZK 5,000 at age 40.
- Take advantage of government and employer incentives. The Czech Long-Term Investment Product (DIP) and supplementary pension savings allow individuals to deduct up to CZK 48,000 annually from their tax base. Many employers also contribute to these plans.
- Build an emergency fund. Renters do not have a property to fall back on during difficult times. Having enough savings to cover several months of expenses is therefore essential before starting to invest.
- Homeownership may still come later. An investment portfolio accumulated over time can also serve as a down payment on a mortgage at age 40 or 45. Renting and investing do not rule out buying a home in the future.
Looking Ahead: The Czech Republic and the World
In the Czech Republic, I do not expect a return to 2% mortgage rates or a significant decline in apartment prices unless housing construction accelerates.
However, two developments could reshape the market in the coming years.
The first is a wave of inheritance. Apartments privatized in the 1990s will gradually pass to today’s generation of people in their thirties and forties.
The second is the expansion of affordable rental housing and the introduction of new building legislation, which could help make renting more affordable and accessible.
The most likely outcome is a model in which young people rent their homes, build investment portfolios, and purchase their first property around the age of 40.
Similar trends are emerging globally.
Every year, Swiss bank UBS compares residential property prices across around 20 major cities, including London, New York, and Munich. According to this year’s comparison, inflation-adjusted property prices have barely increased, as higher mortgage costs have reduced the number of potential buyers. However, housing shortages continue to prevent significant price declines.
In the United States, the typical first-time homebuyer is now 40 years old.
The countries best positioned for the future will be those capable of building enough homes and providing high-quality rental housing, as seen in places such as Vienna and Scandinavia, while also encouraging regular investing as a normal part of financial life.
Conclusion
Our parents built their wealth primarily through homeownership. For part of today’s generation, that will no longer be the case, and it is a reality we cannot simply change.
But not owning a home does not have to mean living without wealth or financial security.
What matters most will not be whether someone owns the place they live in, but whether they have a plan to build wealth over time.
And that is something anyone can start doing, even with just a few thousand Czech crowns a month.
Stone & belter blog
Similar articles
Category
12.10.2026
The Challenges of Buying a Third Property: How Financing Rules Are Changing?
Mgr. Petra Šichová
05.10.2026
From Banker to Advisor: What It’s Like to Start from Scratch After 20 Years
Ing. Lucie Kreperátová

10.09.2026
A Well-Planned Business Owner’s Reserve: Idle Cash or Peace of Mind?
Ing. Marek Jůzl, EFP
19.08.2026
From Elite Sports to Financial Freedom: Why Is It Crucial to Listen to What the Client Isn’t Saying?
Petr Seibot
18.08.2026
Young People and Homeownership: An Unattainable Dream or a Matter of Planning?
Ondřej Marek
05.08.2026
How Investment Selection Reveals Whether a Financial Advisory Firm Is Truly Independent
Ondřej Marek
21.07.2026
Summer is full of great experiences. Just don't let any of them become unnecessarily expensive.
Ing. Tomáš Matucha
12.10.2026
The Challenges of Buying a Third Property: How Financing Rules Are Changing?
Mgr. Petra Šichová
05.10.2026
From Banker to Advisor: What It’s Like to Start from Scratch After 20 Years
Ing. Lucie Kreperátová19.08.2026
From Elite Sports to Financial Freedom: Why Is It Crucial to Listen to What the Client Isn’t Saying?
Petr Seibot05.08.2026
How Investment Selection Reveals Whether a Financial Advisory Firm Is Truly Independent
Ondřej Marek21.07.2026