Poor Millionaires
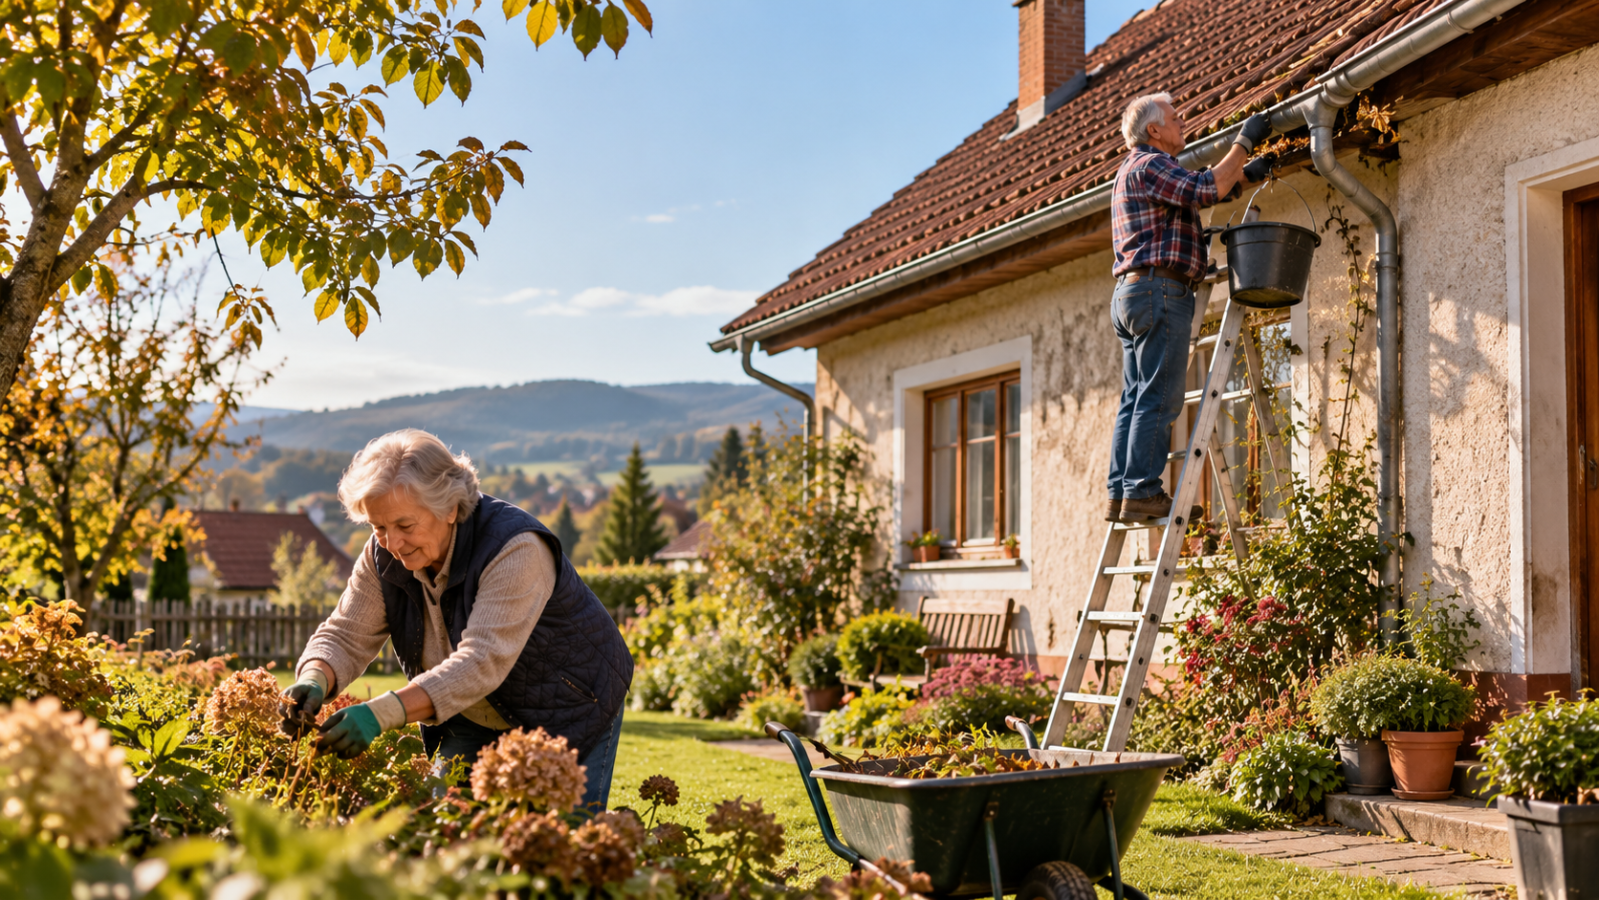
You might be a millionaire. You just don't know it yet.
You own a house worth millions, yet at the end of every month, you're counting every last crown. You have assets, but no cash. That's exactly what it means to be a poor millionaire.
In the Central Bohemian Region, a 140 m² family home could have an estimated value of around CZK 9.7 million. But that money won't pay your gas bills, fix your roof, or buy you a new car. Your wealth is locked up in bricks and mortar.
The average old-age pension in the Czech Republic in 2026 is approximately CZK 21,800 per month. Meanwhile, for a house that's 20 to 30 years old, it's reasonable to budget CZK 50,000–80,000 a year for maintenance. That's roughly CZK 4,000–7,000 a month. And that's before energy bills, property taxes, and insurance.
The numbers aren't particularly encouraging. And the situation won't fix itself.
How Does This Happen?
You built your house for your family. The children were supposed to live upstairs, while you lived downstairs. But then the children moved away — for work, to the city, or simply to build lives of their own. And you were left alone in a large house.
You're paying to heat empty rooms, maintaining the garden, and putting off repairs because you no longer have the money or energy to deal with them.
Yet you're sitting on a property worth millions.
A paradox? Absolutely. Unusual? Not at all.
Selling Your Home and Moving Isn't Just a Financial Decision
Memories. A lifetime of experiences. Friends, neighbours, and a sense of security. Perhaps also the belief that one day you should pass the family home on to your children.
Moving away means leaving behind a place you've known for decades. That's no small thing.
That's why it makes little sense to start by saying, "You should sell your house."
First, you need to understand what your current home gives you, what it costs you, and what options are available.
You might well discover that staying where you are is the best decision. But it should be a conscious choice, not one driven by fear or habit.
What Are Your Options?
One possibility is to sell your large house and buy a smaller apartment or home. Perhaps somewhere closer to your family. Or in a town where doctors, shops, and public transport are within easy reach.
Some of the money could be kept as a financial reserve. Some could be used for travelling, spa breaks, or helping your children. And some could be invested to generate a regular income that supplements your pension.
Instead of owning an asset that costs you money every month, you could have financial resources that give you greater freedom.
It's not about giving up your home. It's about making sure your home doesn't drain your finances.
Start With the Numbers, Not With a Sale
And you don't have to figure it all out on your own!
We're here to help.
Your financial adviser, who has been helping you with insurance and investments for years, will work alongside a colleague from our real estate agency.
One experienced team, working together for you.
We'll review your current situation, discuss your goals, and explore possible solutions.
From determining the market value of your existing property and preparing it for sale to actively helping you find your new house or apartment, we'll be there to guide you through the process.
No pressure. No automatic assumption that your house has to be sold.
You might discover that you're not so poor after all. Your millions are simply tied up in the wrong place.
Note on the figures: The estimated property value is an illustrative calculation based on family home prices in the Central Bohemian Region. The maintenance budget is not a statistical average but a planning estimate for a property aged 20–30 years. Actual costs depend on the location and technical condition of the property.
Stone & belter blog
Similar articles
Category
12.10.2026
The Challenges of Buying a Third Property: How Financing Rules Are Changing?
Mgr. Petra Šichová
05.10.2026
From Banker to Advisor: What It’s Like to Start from Scratch After 20 Years
Ing. Lucie Kreperátová

10.09.2026
A Well-Planned Business Owner’s Reserve: Idle Cash or Peace of Mind?
Ing. Marek Jůzl, EFP
19.08.2026
From Elite Sports to Financial Freedom: Why Is It Crucial to Listen to What the Client Isn’t Saying?
Petr Seibot
18.08.2026
Young People and Homeownership: An Unattainable Dream or a Matter of Planning?
Ondřej Marek
05.08.2026
How Investment Selection Reveals Whether a Financial Advisory Firm Is Truly Independent
Ondřej Marek
21.07.2026
Summer is full of great experiences. Just don't let any of them become unnecessarily expensive.
Ing. Tomáš Matucha
12.10.2026
The Challenges of Buying a Third Property: How Financing Rules Are Changing?
Mgr. Petra Šichová
05.10.2026
From Banker to Advisor: What It’s Like to Start from Scratch After 20 Years
Ing. Lucie Kreperátová19.08.2026
From Elite Sports to Financial Freedom: Why Is It Crucial to Listen to What the Client Isn’t Saying?
Petr Seibot05.08.2026
How Investment Selection Reveals Whether a Financial Advisory Firm Is Truly Independent
Ondřej Marek21.07.2026